

Reverse Mortgages — HECM & Hybrid
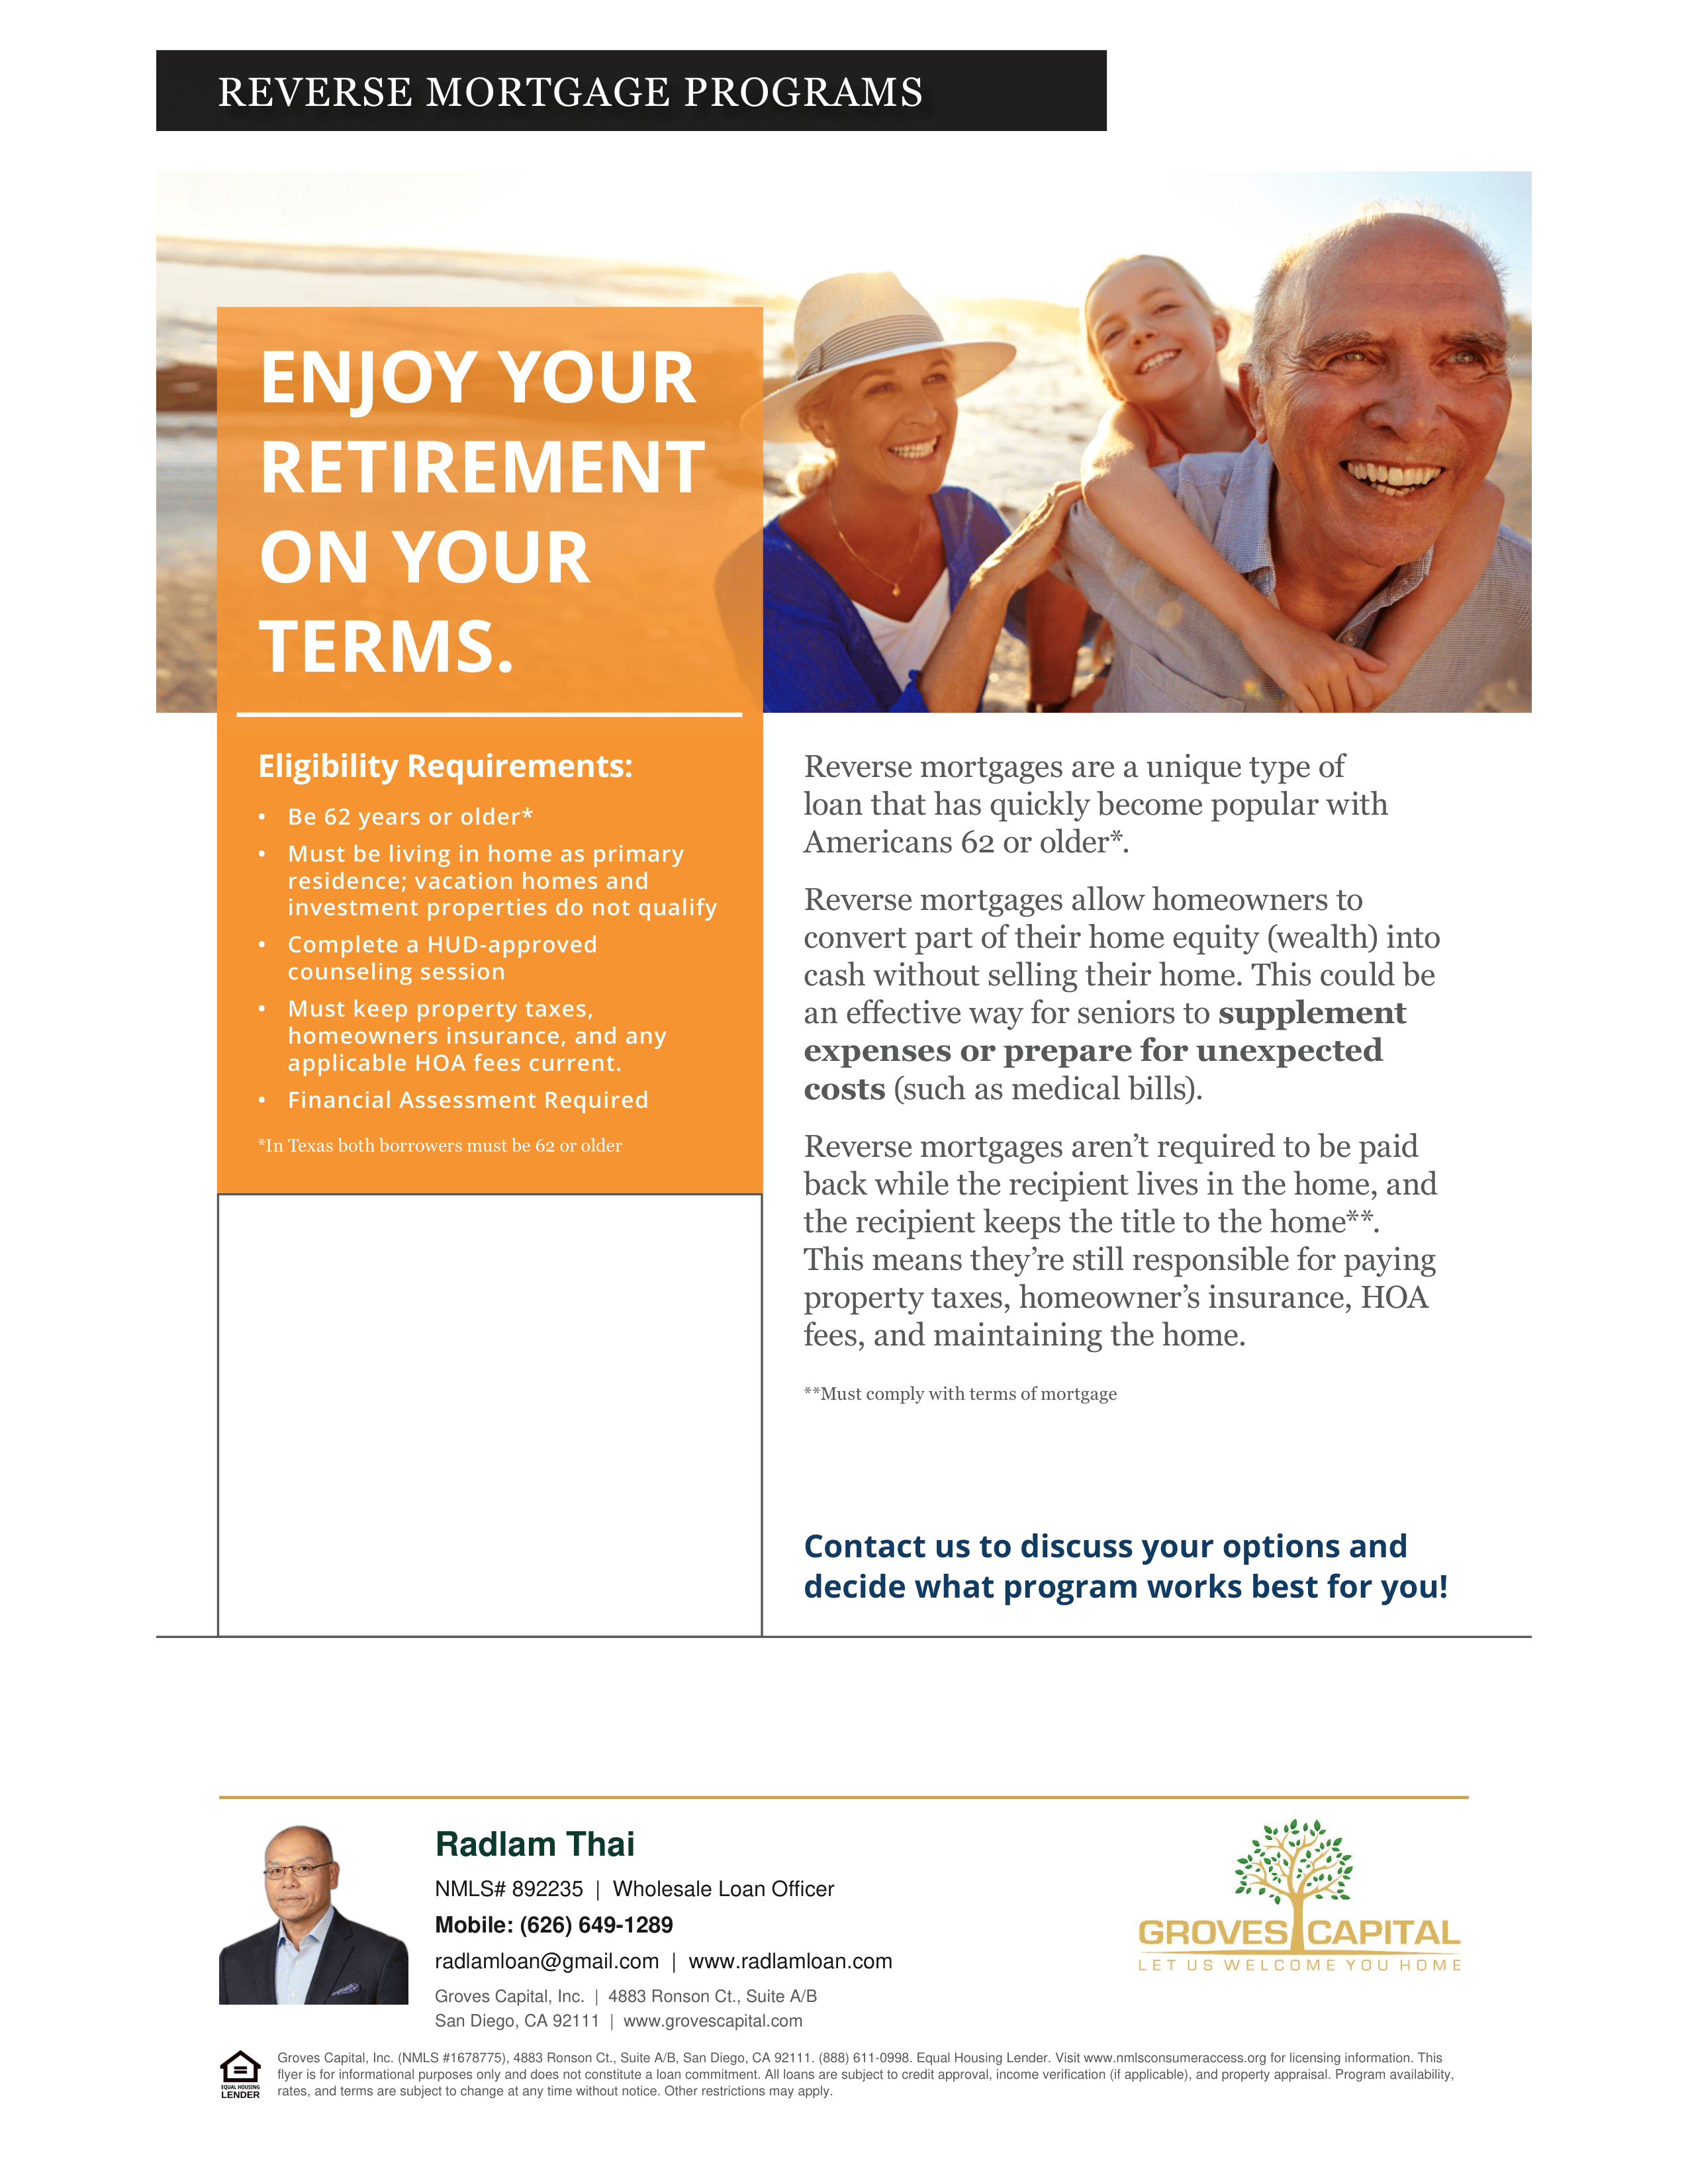
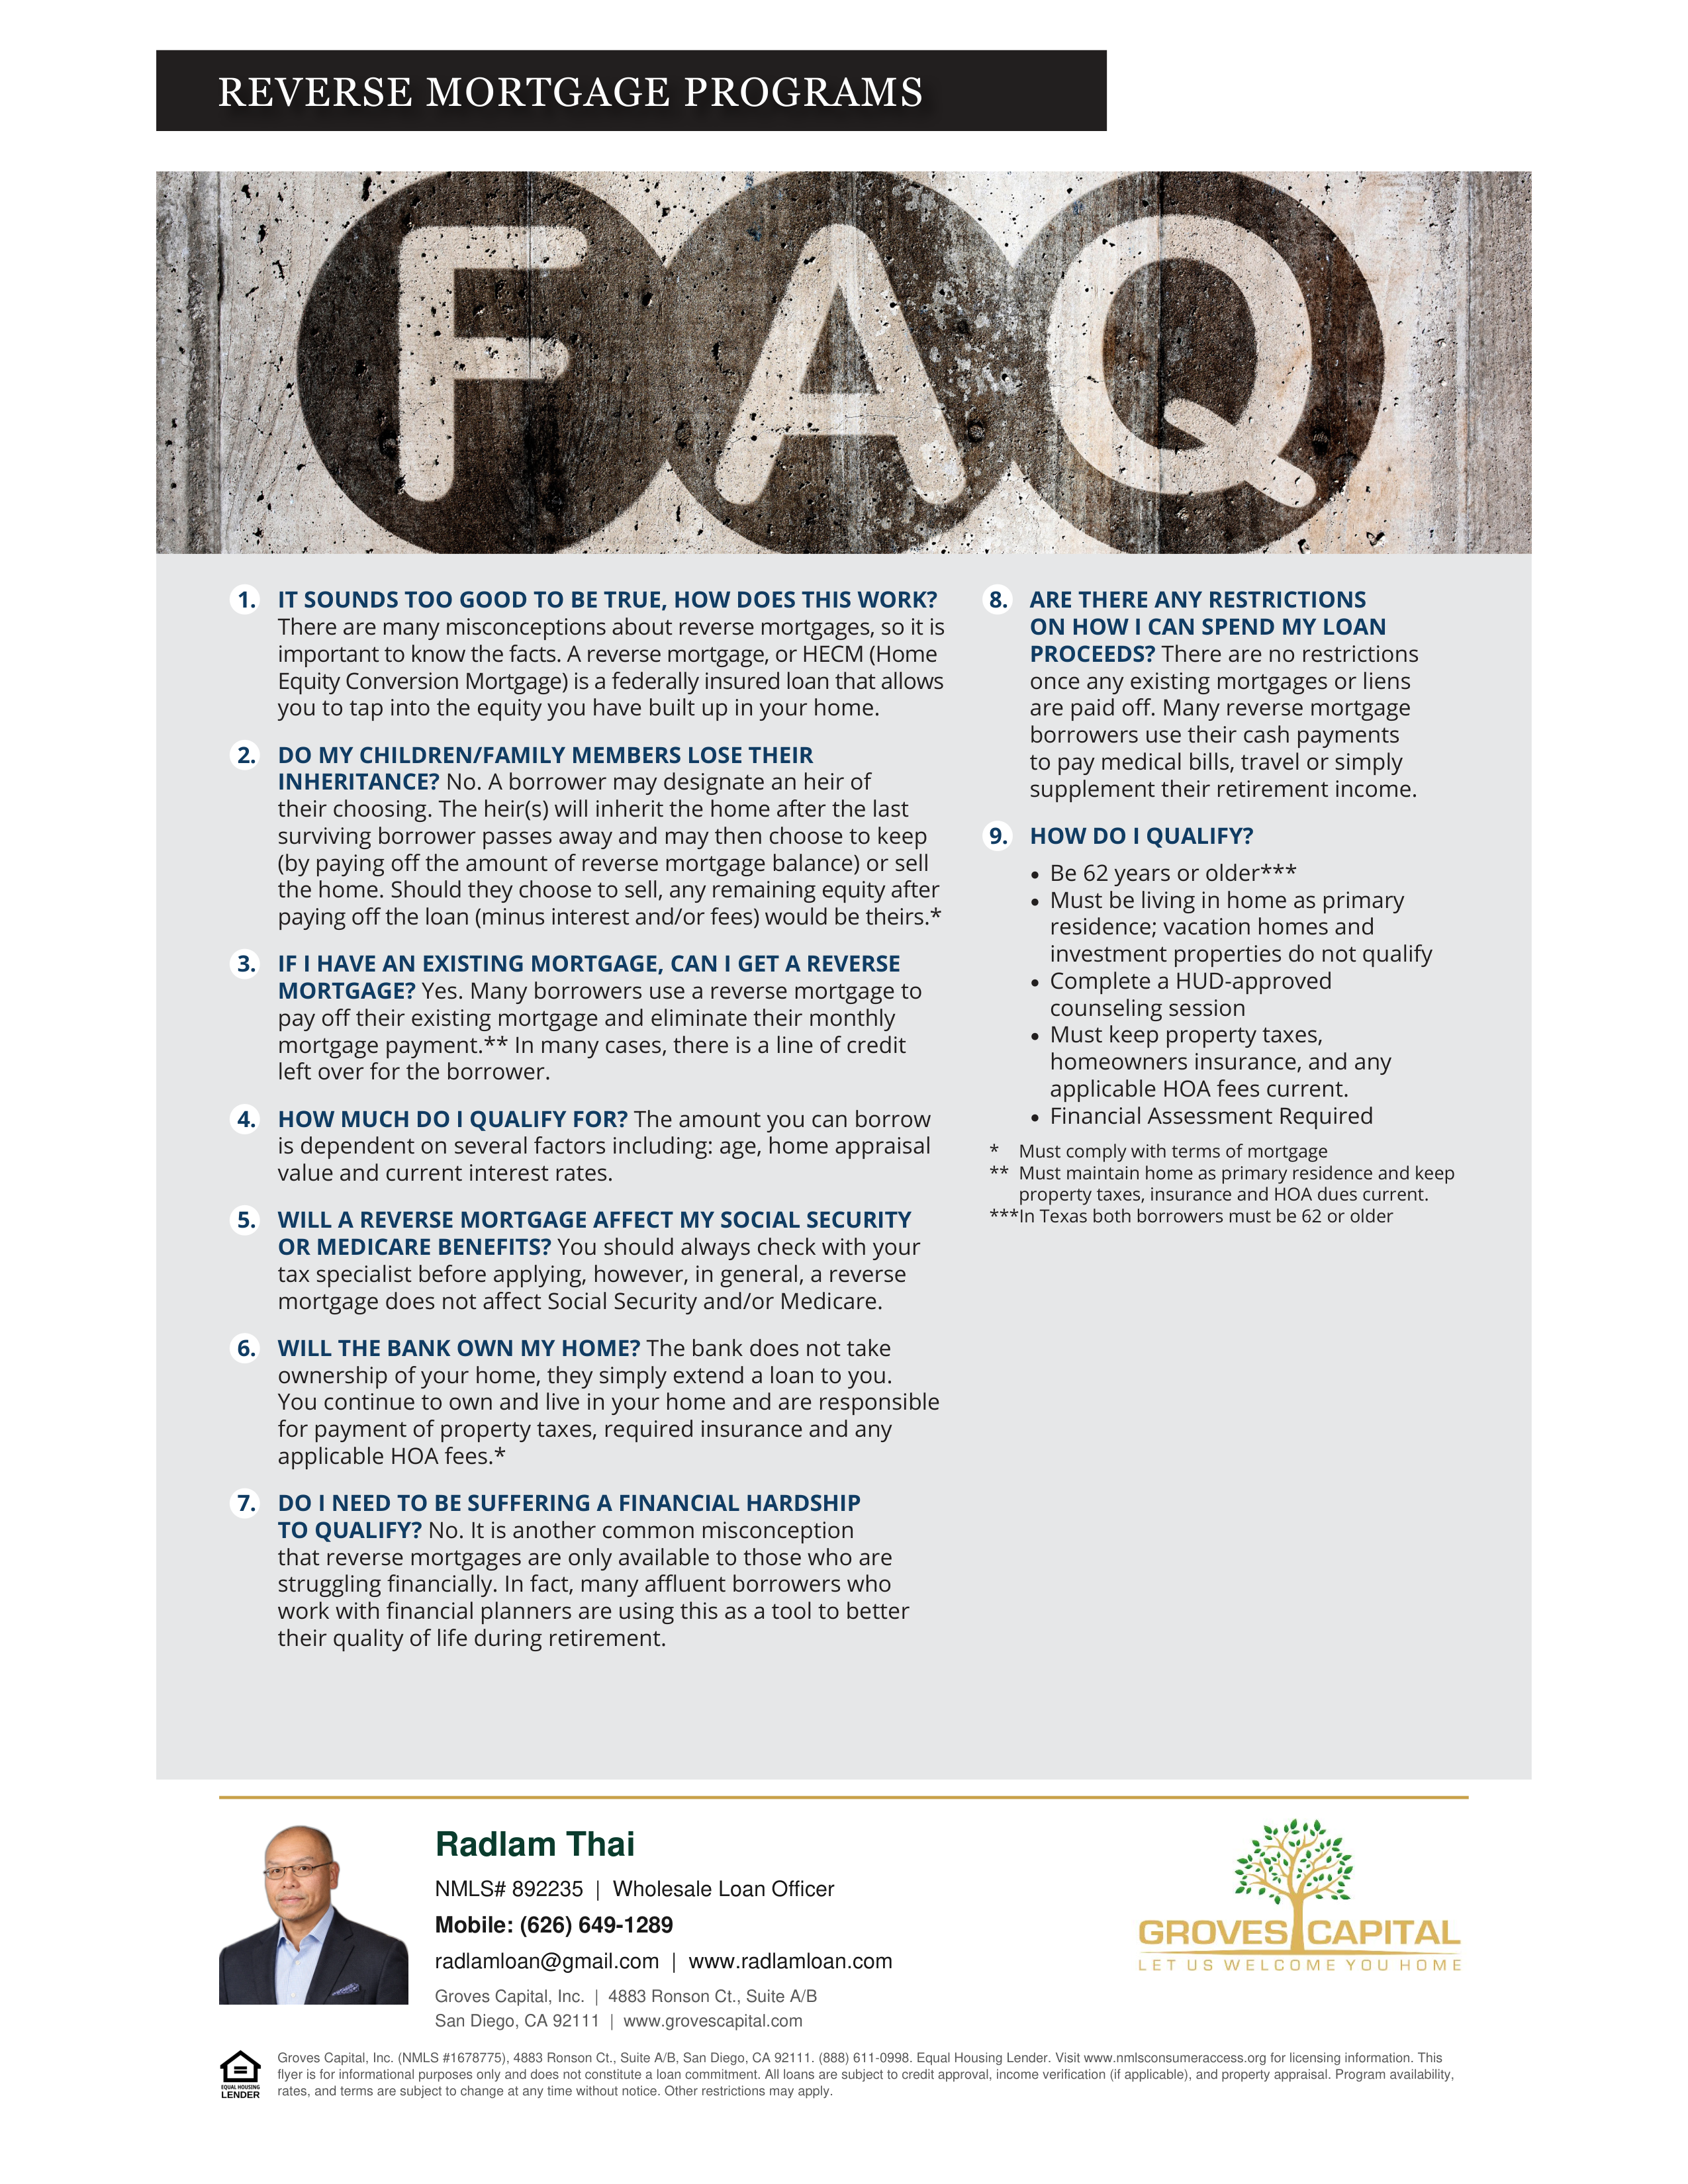
A reverse mortgage lets homeowners 62 and older convert part of their home equity into cash — with no monthly mortgage payment required. It’s a powerful retirement planning tool when structured correctly, and I’ll make sure you understand exactly how it works before you decide.
Who It’s For
- Homeowners age 62+ who want to supplement retirement income
- Retirees looking to eliminate their monthly mortgage payment
- Homeowners with significant equity who want financial flexibility
Reverse Mortgage Options I Offer
- HECM (Home Equity Conversion Mortgage) — the FHA-insured reverse mortgage, the most common and most consumer-protected option
- HomeSafe Standard — a proprietary (jumbo) reverse mortgage for higher-value homes above HECM lending limits
- HomeSafe Select — a proprietary option designed for borrowers who want a lower-cost alternative with flexible payout structures
- EquityAvail — a hybrid reverse mortgage option for homeowners 55+ seeking additional flexibility
Key Features
- No monthly mortgage payment required — the loan is repaid when you sell, move, or pass away
- Receive funds as a lump sum, monthly payments, a line of credit — or a combination
- You retain title and ownership of your home
- Non-recourse: you (or your heirs) will never owe more than the home’s value
- Mandatory HUD-approved counseling ensures you understand the program
A reverse mortgage is a big decision — I’ll give you straight answers, involve your family or advisors if you’d like, and never pressure you. If it’s not the right fit, I’ll tell you.
Program Flyers




Latest Reverse Mortgage Insights
-

Reverse Mortgages: Should Retirees Consider One? | Mortgage & Real Estate Updates: VA, FHA, HELOC, DSCR, 1099, P&L, Hard Money, Land, Farm, Fix & Flip, No-Docs, Commercial Loan
When buyers cannot qualify for a mortgage, some turn to land contracts, a seller-financing option that often leaves them with fewer legal protections. Researchers found land contracts were commonly used when traditional mortgages were harder to obtain for low-cost homes, manufactured homes, rural properties, and older fixer-uppers. The central takeaway was straightforward: better mortgage access…
-
How much equity do you need for a reverse mortgage?
Homeowners aged 62 or older typically need 50% to 60% home equity to qualify for a reverse mortgage, with government-backed HECMs requiring 50%. Reverse mortgages allow tapping home equity for cash without monthly payments, but payment is due upon selling, moving, or death. Risks include foreclosure if property taxes or insurance aren't paid. Benefits include…
-

California Reverse Mortgages: What to Know | Follow for Updates on Mortgage & Real Estate News. We Specialize in Low-Credit FHA & No/Low-Credit VA Loans.
Reverse mortgages (HECM) are FHA-insured loans for Californians aged 62+, using primary home equity. Borrowers can withdraw funds as a lump sum or in installments for any purpose. Property taxes and insurance must be paid; no ongoing mortgage payments are required. Loan repayment occurs when the borrower dies or no longer occupies the home. Communication…